Freight Warning Meets Retail Surge: The IYT ETF Trade
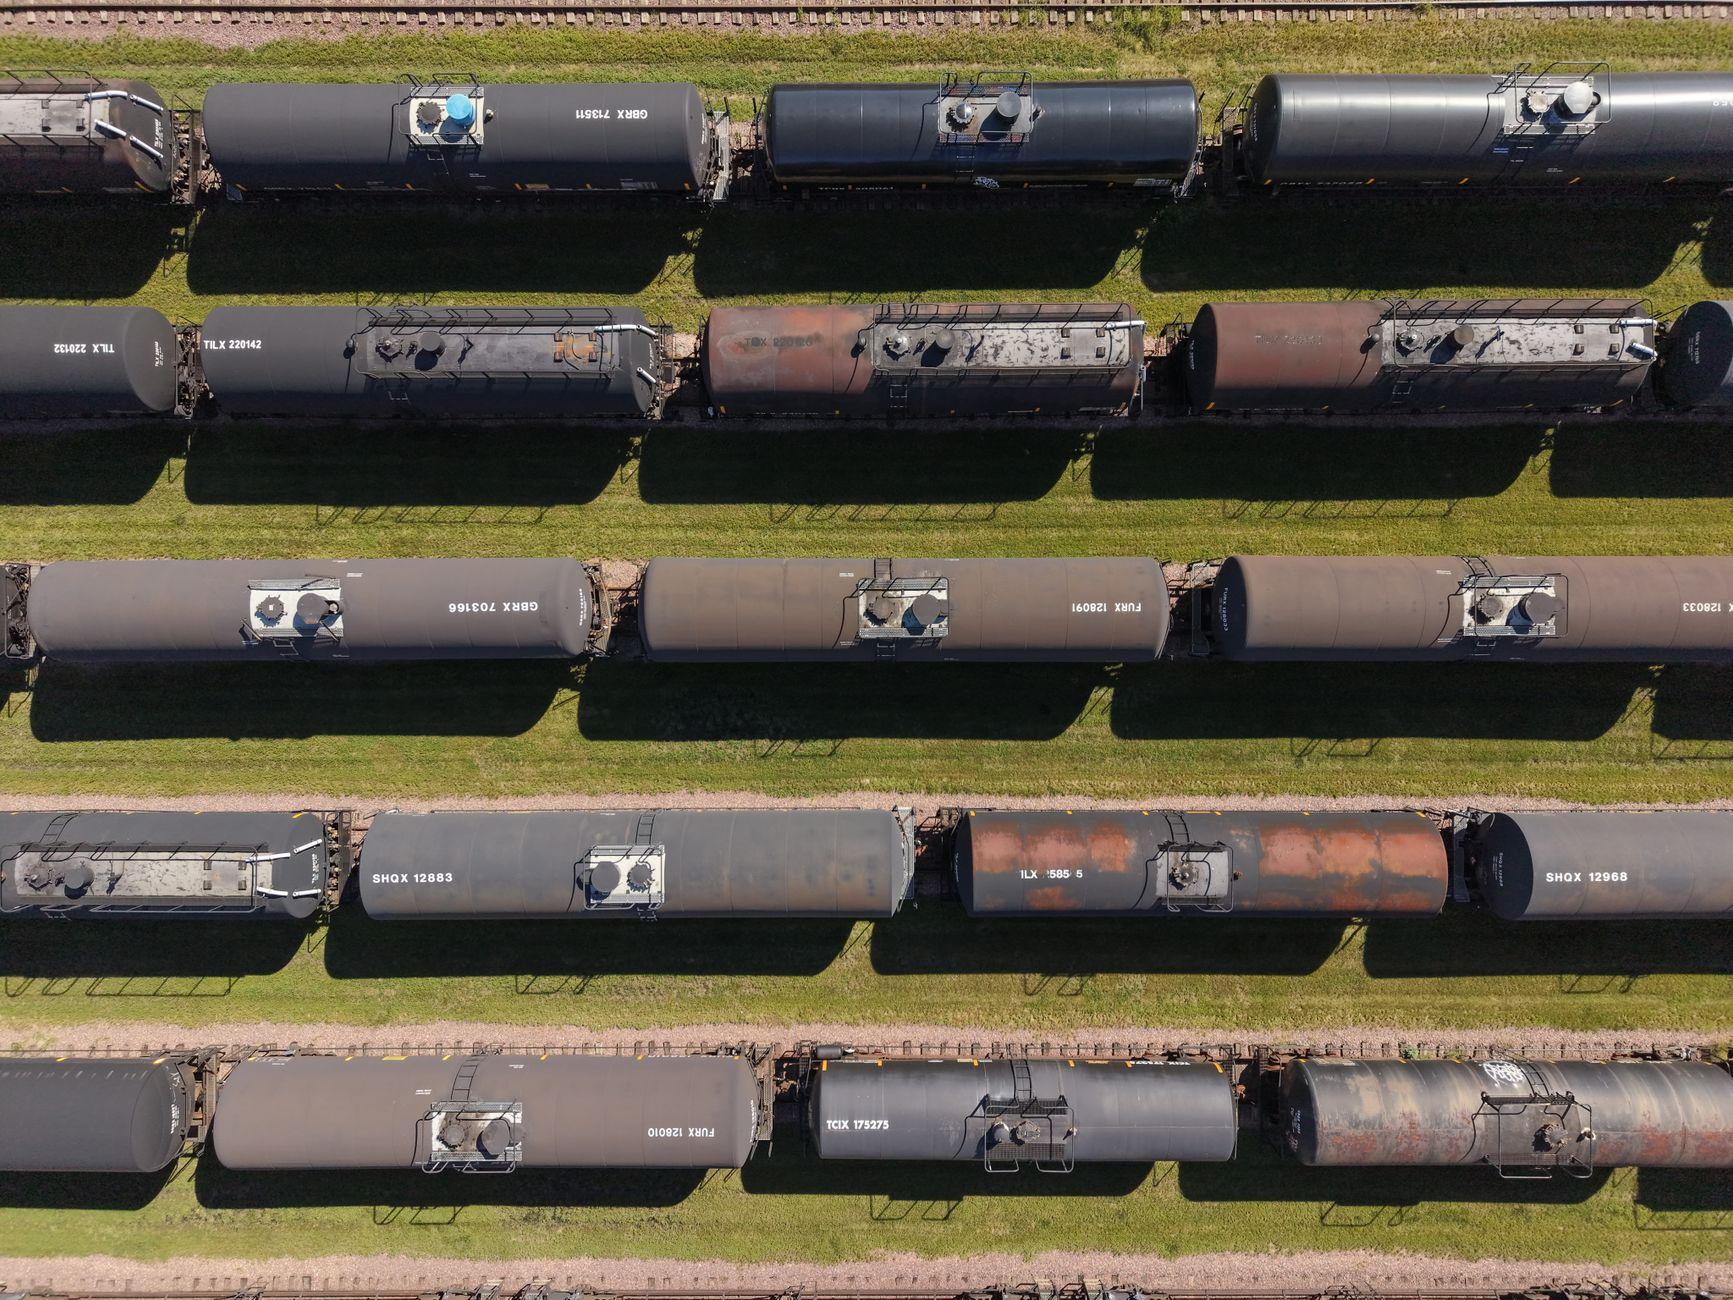
A trucking CFO warning clashes with surging retail sales on Fed hike day. How to trade the IYT ETF put spread and what freight signals mean for markets.
What this means for the cycle — and for the IYT ETF, the Dow Jones Transportation benchmark every freight-watcher should have open right now — is the question no one wants to answer honestly on a day like today.
A major S&P 500 trucking name cratered after its CFO said what trucking CFOs rarely say out loud: demand is deteriorating. Simultaneously, August retail sales printed hot enough to give the consumer-still-fine crowd exactly the ammunition they needed. And into all of this walks the Federal Reserve, expected to deliver its first rate hike in three years — a policy pivot that rewrites every duration trade on the board.
Three signals. Three different stories. One session.
The freight-versus-retail divergence is not a novelty. It has appeared before, and history has a decided view on which side tends to be right.
Do Trucking Stocks Predict Recessions Before They Happen?
The short answer is yes, and the data is uncomfortably consistent.
Freight volumes have historically led broad economic activity by six to eight weeks. The mechanism is straightforward: retailers order goods, trucking companies move them, and when trucking companies start warning about load counts and spot rates, those goods were already not ordered. By the time consumers feel the pinch, the trucking sector has been in distress for two months.
The 2021–2022 cycle provided the textbook illustration. Trucking stocks peaked in late 2021, CFOs at major carriers flagged softening demand by the first quarter of 2022, and the broader recession scare materialized in almost exactly the window that freight had signaled. The IYT ETF topped out ahead of the S&P 500 by a meaningful margin, and anyone watching spot rates in real time had the warning well before consensus caught up.
Today's CFO warning fits that template uncomfortably well. A single executive speaking plainly about deteriorating conditions is worth more than three consensus estimates, because executives carry legal liability for what they say publicly. They do not cry wolf.
What Does a CFO Freight Warning Mean for the Broader Market?
Context matters. One trucking company's guidance miss is not a recession call. But pattern recognition is part of this job, and the pattern is this: when stagflation signals map onto freight and labor costs in the way they currently are — elevated unit labor costs, compressed carrier margins, spot rates rolling below contract rates — the CFO warning is not isolated noise. It is confirmation of a thesis already forming in the data.
The broader S&P 500 transportation sector is worth watching in that light. SPY closed at 757.4, down half a percent on the session and off 1.1% over five sessions, while trading below its 50-day moving average of 759.1. That 50-day is where the short-term trend sits, and bulls need to reclaim it to restore confidence in the tape. The structural floor is the 200-day at 715.1, which remains intact and provides ballast for the longer view. Volume ran at 46.2 million shares against a 20-day average of 38 million, meaning participation was above-average in a declining session. Distribution on elevated volume is not how healthy markets behave. The support level near 729.1 is the number that matters if sellers press; resistance near 779.4 capped the recent range and has not been seriously tested since.
The market is not in freefall. But these are precisely the conditions in which a single freight canary moves from anecdote to thesis.
Is the Retail Sales Surge Hiding a Coming Economic Slowdown?
This is the more interesting question, because the retail sales data was genuine. It printed strong, and the consumer does not appear to be retrenching yet.
The resolution of the freight-versus-retail divergence historically comes one of two ways. Either the trucking sector was early — demand softened briefly, restocking followed, and the carrier warning became a one-quarter aberration — or the retail data was measuring a last burst of spending before conditions tightened. The second scenario is harder to trade because consumer spending lags freight by approximately the same margin that freight leads the economy. Retail sales today may be measuring orders placed six weeks ago, when sentiment was still buoyant and credit was still flowing freely.
The current setup carries one additional complication. The Fed hike playbook every retail trader needs today looks different when the transportation sector is already exhibiting stress at the moment of liftoff. In 2018, when the Fed continued hiking into late-cycle conditions, the first cracks appeared in exactly these kinds of operationally sensitive businesses — companies with high fixed costs and variable revenue tied directly to economic throughput. The sequence then was not a clean break; it was a slow deterioration that looked like noise until it didn't.
The retail sales surge may be real and durable. It may also be the last strong print before freight's warning proves prescient. Both remain live hypotheses, and the Fed decision today will not cleanly resolve either of them.
How Do You Trade a Put Spread on IYT ETF?
The setup being discussed on the desk is a defined-risk put spread on the IYT ETF, structured to profit if the freight signal proves correct and the transportation sector underperforms over the next six to eight weeks.
The logic of using a spread rather than an outright put is discipline, not timidity. If the Fed hike today sparks the kind of relief rally that rates-optimism trades can generate — shorts covering, positioning normalizing — an outright put position bleeds quickly and emotionally. A put spread defines the maximum loss at the premium paid before the trade opens. That allows a trader to hold through post-Fed volatility without the position threatening the broader book.
The structure involves buying a put at or slightly below the current level in IYT and selling a lower-strike put to offset the cost. The width of the spread reflects conviction about how far the ETF can move if the freight thesis plays out over the signal's historical lead time. The stop is implicit in the structure itself: if IYT reclaims the upper end of its recent range with conviction and holds it, the thesis is wrong, and the defined-risk nature of the spread means that loss was already quantified at entry.
The individual trucking name that triggered today's selloff presents the same binary at the single-stock level. A one-quarter-early CFO who gets the timing wrong is eventually vindicated; a stock that craters on guidance often stabilizes and recovers when the rest of the data catches up. The dip may be a gift. The dip may also be the beginning of something longer. That ambiguity is precisely why the spread — not the directional bet — is the appropriate vehicle when directional conviction is high but timing humility is warranted.
For traders who want to screen transportation and sector breakouts live on Traderise before the post-Fed tape resolves the picture, the key observation is this: watch whether the next rally attempt into resistance attracts sellers or finds buyers willing to step in with genuine participation. A close that fails to reclaim the session's earlier highs following the rate decision would be a materially different signal than one that reverses cleanly on relief. The 729.1 support on SPY is the line that separates a controlled pullback from a more consequential breakdown — that level is the one to hold if the bulls have any intention of defending the range.